

LITELumentum Holdings Inc
Company Overview
Name
52W High
52W Low
Market Cap
Dividend Yield
Price/earnings
P/E
Tags


Dividends
No dividend
Sentiment
Score
Mixed
44
Low
Neutral
High
0
50
100
Trade Volume
Score
Neutral
50
Low
Neutral
High
0
50
100
Income Statement
Total Revenue
Operating Revenue
Total Gross Profit
Total Operating Income
Net Income
EV to EBITDA
EV to Revenue
Price to Book value
Price to Earnings
Additional Data
Selling, General & Admin Expense
Research & Development Expense
Other Operating Expenses / (Income)
Restructuring Charge
Total Operating Expenses
Interest Expense
Earnings History
- Estimated
- Reported, beat
- Reported, missed
Estimated EPS
Reported EPS
N/ACompany Overview
Name
52W High
52W Low
Market Cap
Dividend Yield
Price/earnings
P/E
Tags
Dividends
No dividend
Sentiment
Score
Mixed
44
Low
Neutral
High
0
50
100
Trade Volume
Score
Neutral
50
Low
Neutral
High
0
50
100
Income Statement
Total Revenue
Operating Revenue
Total Gross Profit
Total Operating Income
Net Income
EV to EBITDA
EV to Revenue
Price to Book value
Price to Earnings
Additional Data
Selling, General & Admin Expense
Research & Development Expense
Other Operating Expenses / (Income)
Restructuring Charge
Total Operating Expenses
Interest Expense
Earnings History
- Estimated
- Reported, beat
- Reported, missed
Estimated EPS
Reported EPS
N/AUpcoming Earnings
Company Info
CEO
Alan S. Lowe
Location
California, USA
Exchange
Nasdaq
Website
https://lumentum.com
Summary
Lumentum Holdings Inc.
Company Info
CEO
Alan S. Lowe
Location
California, USA
Exchange
Nasdaq
Website
https://lumentum.com
Summary
Lumentum Holdings Inc.
Community Research
Research from investors like you
Be the first to share your analysis on LITE
Help fellow investors make informed decisions by sharing your research on fundamentals, catalysts, and outlook.
Symbol's posts


The AI Optics Supply Chain Has a Bigger Problem Than Demand
The AI Optics Supply Chain Has a Bigger Problem Than Demand
Reuters reported that the US administration is moving ahead with a proposed ban on new Chinese optical transceiver imports, despite major cloud companies pushing back. Chinese suppliers account for roughly two thirds of the global market, and the US alternatives simply don't have enough capacity to replace that volume quickly. Some companies have warned the transition could take up to a decade.
Coherent and Lumentum could benefit from a shift toward Western suppliers. and are worth watching here, but I wouldn't assume this automatically means a flood of new orders. These components require manufacturing capacity, reliable yields and customer qualification. You can't just switch suppliers overnight because Washington changes a rule.
There's another risk that I think deserves attention which is that China could respond by restricting exports of indium phosphide, a key material used in optical components. That would make the supply chain problem even more complicated.
I'm interested in this because it shows how much of the AI buildout depends on relatively small hardware components that most investors barely think about. A policy decision meant to secure data centers could end up slowing their expansion if replacement capacity isn't ready. That's a pretty uncomfortable tradeoff.

Overview of 6 companies working on AI data center connectivity
Overview of 6 companies working on AI data center connectivity
www.fool.com
| Data Centers Need Faster Connections. These 6 Optical and Networking Stocks Could Benefit. | The Motley Fool
Lumentum Is Becoming a Bigger AI Infrastructure Play
Lumentum Is Becoming a Bigger AI Infrastructure Play
Lumentum is getting more attention as AI data centers drive stronger demand for optical networking and faster connectivity. The interesting part is how much of the AI infrastructure spending is moving beyond GPUs into the components needed to connect everything together

Jim Cramer Says the AI Trade Is Back
Jim Cramer Says the AI Trade Is Back
The AI infrastructure trade is showing some serious strength again, and is leading the group alongside , , , and . After a rough stretch, all six stocks bounced sharply, with investors getting more confident in AI demand again. What stands out is that the rebound isn’t just about hype, better earnings, strong AI demand and softer inflation are all helping the group regain momentum. Do you think this is the start of another AI rally, or is it too early to chase these stocks after such a big bounce?

Watching Lumentum Holdings today
Watching Lumentum Holdings today
lumentum holdings is seeing a nice jump today following that barclays upgrade. i'm curious if is finally stabilizing enough to be a good long-term play for ai networking.

$LITE I’m less interested in guessing tomorrow and more interested in whether Q3 becomes the new normal.
$LITE I’m less interested in guessing tomorrow and more interested in whether Q3 becomes the new normal.
44% gross margin + positive FCF looks great. Question is whether AI optics demand can keep that going for a few quarters.

Lumentum expanding its US manufacturing
Lumentum expanding its US manufacturing
It is really interesting to see Lumentum scaling up their US laser production to keep up with the massive AI data center demand. I am curious if these long-cycle commitments will give a real advantage over its competitors in the long run. Does anyone else here follow the optics space closely?

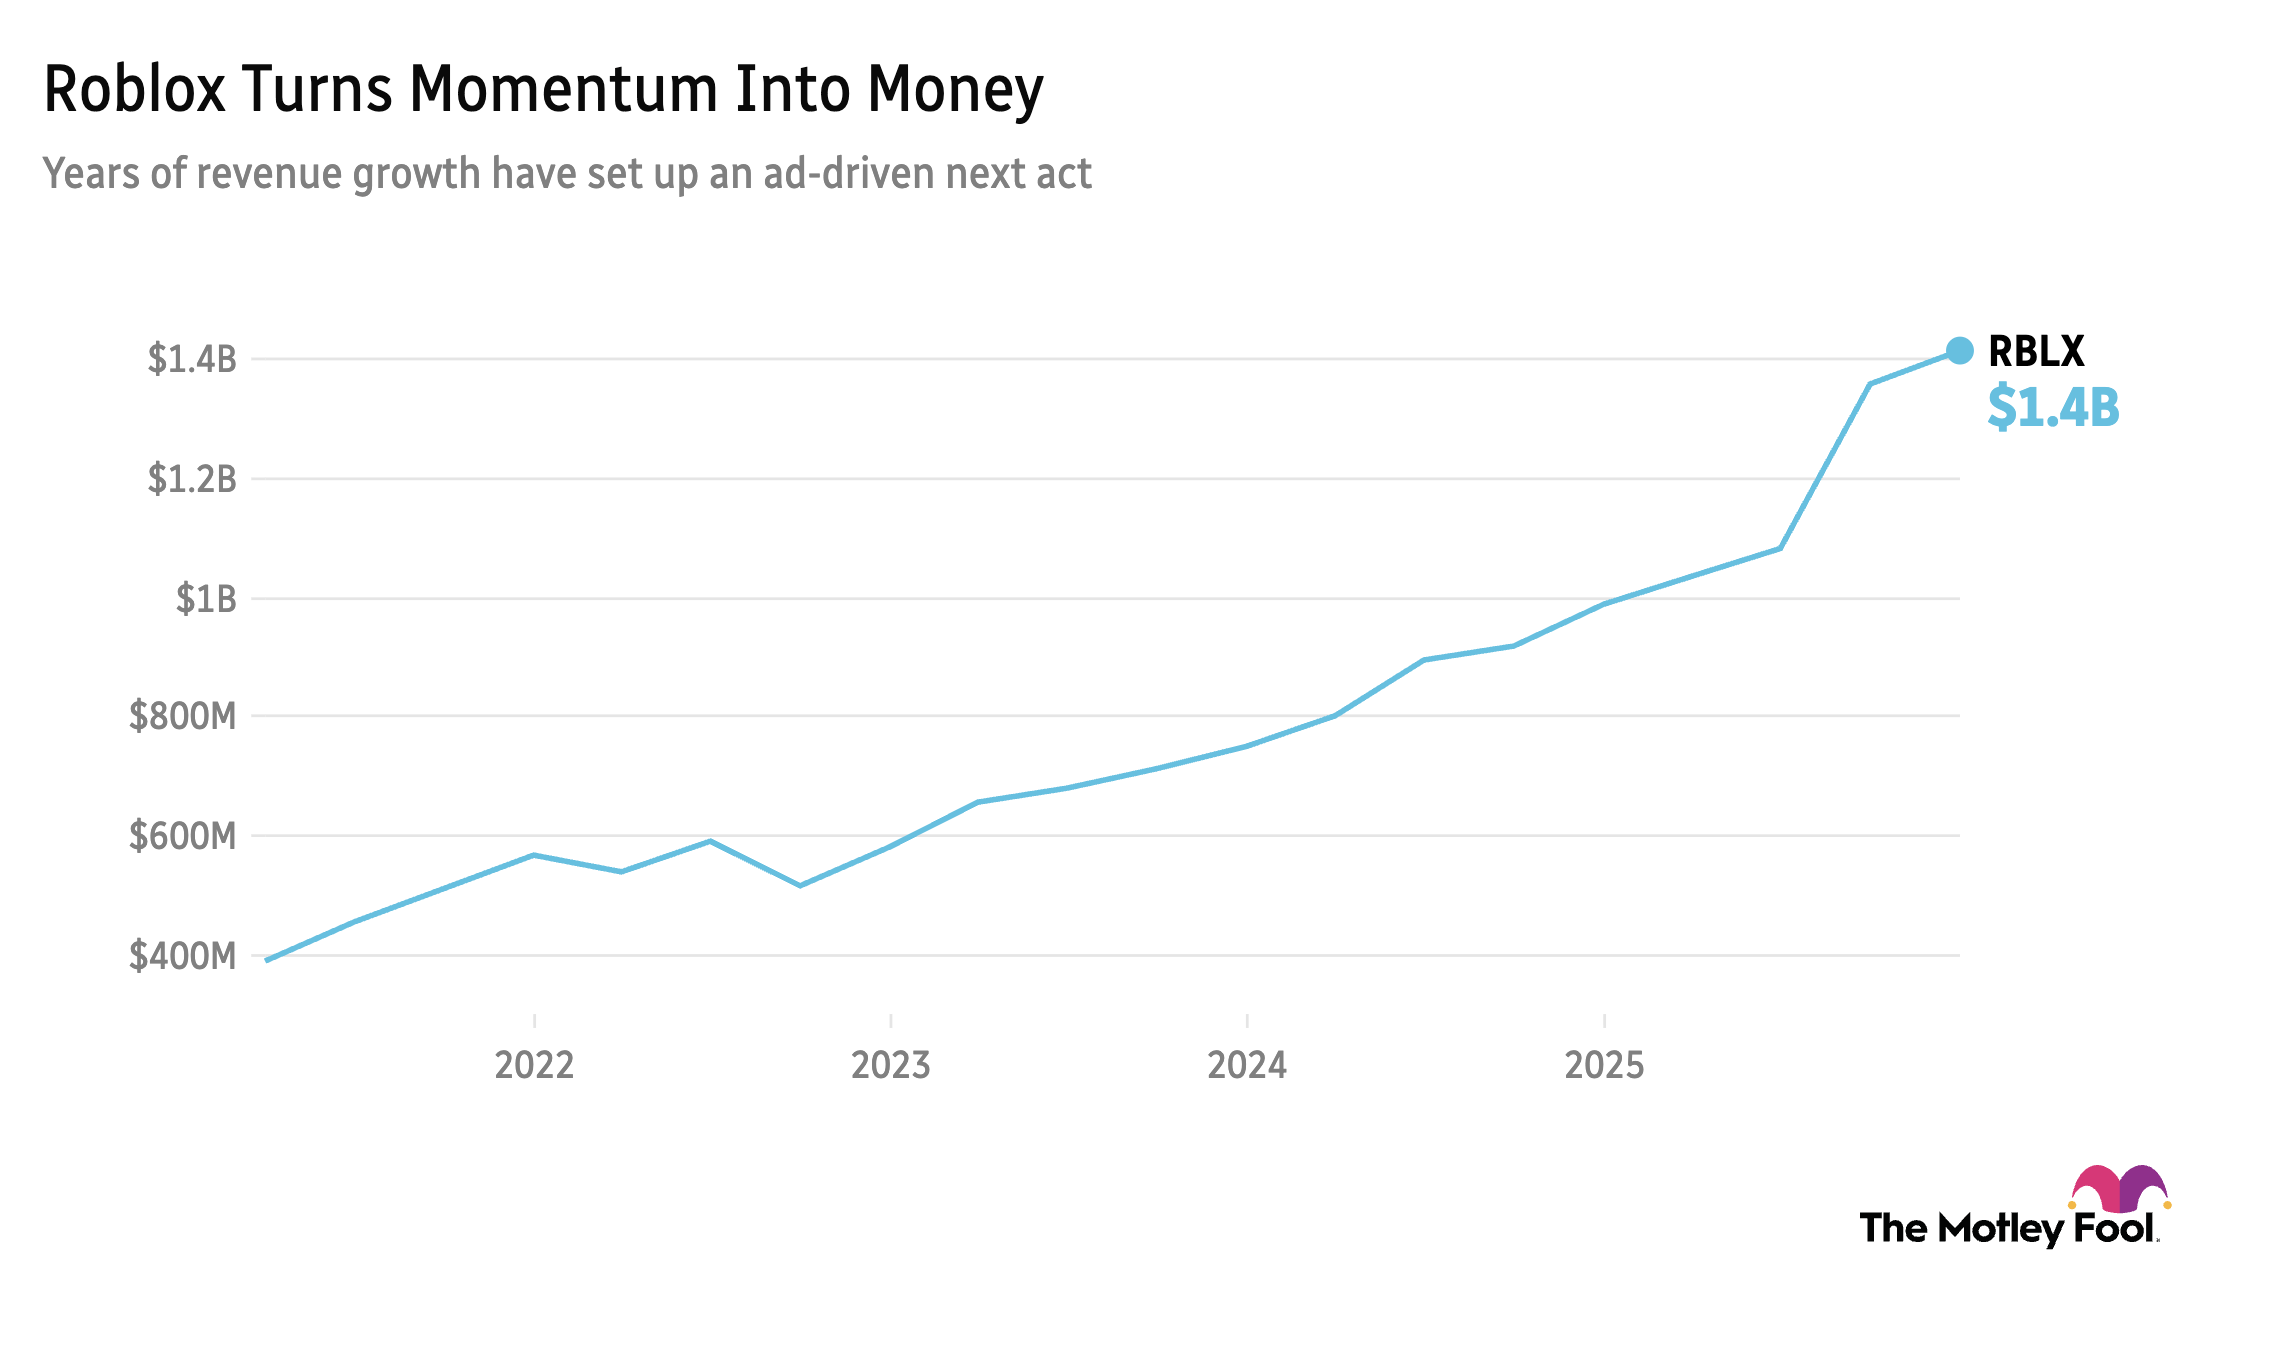
Market update: Oil climbs on Middle East conflict, S&P down for fourth week
Market update: Oil climbs on Middle East conflict, S&P down for fourth week
www.fool.com
| Stock Market Today (LIVE): The Reality of Investing in 2026; Roblox Takes Aim at Brand Deal Pricing | The Motley Fool
LITE returns to profitability in Q2 FY26, raises outlook
LITE returns to profitability in Q2 FY26, raises outlook
finance.yahoo.com
| Lumentum Profit Return And Growth Outlook Fuel Undervaluation Debate
No more topics to show