KBHKB Home

Upcoming Earnings

We were not able to find an announced earnings date for this symbol yet. Check back again later

Company Info

CEO

Jeffrey T. Mezger

Location

California, USA

Exchange

NYSE

Website

https://kbhome.com

Summary

KB Home operates through four segments: West Coast, Southwest, Central, and Southeast.

Company Info

CEO

Jeffrey T. Mezger

Location

California, USA

Exchange

NYSE

Website

https://kbhome.com

Summary

KB Home operates through four segments: West Coast, Southwest, Central, and Southeast.

AI Insights for KBH
5 min read

Quick Summary

KB Home is a U.S. homebuilder headquartered in Los Angeles, California, and operates through West Coast, Southwest, Central, and Southeast segments. The company builds and sells attached and detached single-family homes, townhomes, and condominiums. Its main customers are individual homebuyers, including first-time buyers, move-up buyers, and families seeking newly constructed residential housing. KB Home also provides related financial services, including insurance products and title services, which help support the home purchase process. The company is tied closely to the health of the U.S. housing market, mortgage affordability, consumer confidence, and regional employment trends.

Strengths

•

KB Home’s main strength is its established brand and long operating history in U.S. homebuilding.

•

The company has geographic diversification across West Coast, Southwest, Central, and Southeast regions, which reduces dependence on any single local housing market.

•

Its built-to-order model can differentiate the company by giving buyers more personalization and potentially improving customer satisfaction.

•

KB Home also has a shareholder-return angle through dividends and significant buyback authorization, which may appeal to value-oriented investors.

•

Its valuation appears relatively low on book value and earnings metrics, which can provide upside if the housing cycle stabilizes and margins recover.

Key Risks

•

The biggest external risk for KB Home is a prolonged period of high mortgage rates, which would keep affordability strained and reduce demand for new homes.

•

Economic weakness, job losses, or declining consumer confidence could also cause buyers to delay purchases or cancel contracts.

•

Competition from large builders using aggressive incentives, rate buydowns, and price cuts could pressure KB Home’s margins and market share.

•

Internal execution risk is also meaningful because the success of the built-to-order model depends on construction efficiency, cost control, cycle times, and accurate demand forecasting.

What to Watch

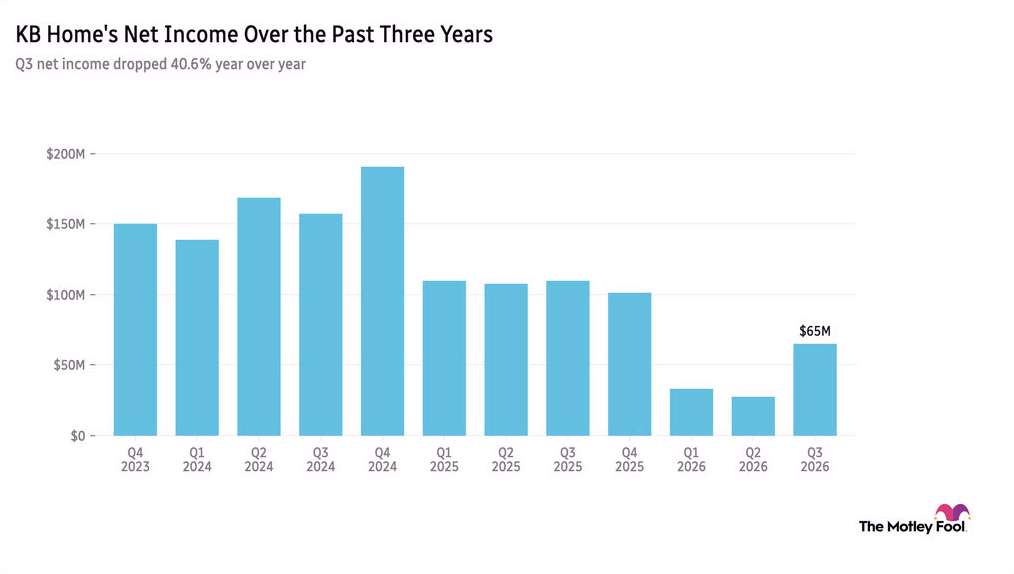
In the most recent provided quarter, KB Home reported operating revenue of about $1.30 billion, total gross profit of about $218.5 million, operating income of about $70.4 million, and net income of about $65.3 million.
Diluted EPS was reported at $1.05, while basic EPS was $1.07, reflecting profitability but also highlighting pressure versus stronger prior housing-cycle periods.
News around the company emphasized a strategic shift back toward a built-to-order model, which management argues can improve cost certainty, reduce cancellations, and eventually support margins.
Analysts also noted weak quarterly results, margin pressure, inventory impairments, price cuts, low backlog, and intense competition from peers using mortgage-rate buydowns.
The quarter also featured investor attention on capital returns, including share repurchases and a dividend yield of about 2.16%.

Price Drivers

•

KB Home’s stock price is driven primarily by expectations for home deliveries, orders, backlog, revenue, gross margins, and earnings per share.

•

Mortgage rates are a major driver because higher rates reduce affordability and can weaken buyer traffic, while lower rates can quickly improve demand.

•

Recent news shows mixed investor sentiment, with bulls focusing on cost cuts, buybacks, stabilizing housing conditions, and a fair value estimate around $68, while bears focus on weak demand, margin pressure, price cuts, and backlog concerns.

•

The company’s valuation metrics, including a price-to-earnings ratio near 12.37 and price-to-book value near 0.74, can attract value investors if they believe earnings are sustainable.

•

Share repurchases, including the reported authorization of up to $1 billion in buybacks, may support the stock, but weak earnings revisions or reduced EPS forecasts can pressure shares.

Recent News

•

Recent news on KB Home has been mixed, with some analysts raising fair value estimates while others downgraded the stock after weak results.

•

Bulls have cited better execution, cost cuts, buybacks, stronger margins, and a potentially stabilizing housing cycle.

•

Bears have pointed to weak demand, margin pressure, inventory impairments, price reductions, low backlog, and tougher competition from builders offering mortgage-rate buydowns.

•

Raymond James reportedly downgraded KB Home to Market Perform and reduced its FY26 EPS forecast to $3.60 from $6.45, reflecting concern about profitability and the built-to-order transition.

•

Other reports noted that KB Home shares rose when management highlighted the potential benefits of the built-to-order model despite weak revenue, deliveries, and profit trends.

Market Trends

•

The broader homebuilding market is being shaped by high home prices, elevated mortgage rates, limited affordability, and cautious consumer behavior.

•

New-home sales have weakened in some periods, inventories have risen, and builders have responded with price cuts, incentives, and mortgage-rate buydowns.

•

At the same time, the United States continues to face a structural housing shortage, which supports long-term demand for new construction if buyers can afford monthly payments.

•

Public homebuilders with scale may be better positioned to manage costs, secure land, and offer incentives than smaller private builders.

•

KB Home’s outlook depends on whether near-term affordability headwinds ease before competitive pressure and margin erosion offset the benefits of long-term housing demand.

AI-generated summary for educational purposes only. Not investment advice. Always do your own research before investing.

Community Research

Research from investors like you

Be the first to share your analysis on KBH

Help fellow investors make informed decisions by sharing your research on fundamentals, catalysts, and outlook.

Topics: Company overview • Products • Competitors • Strengths & Risks

Symbol's posts

avatar
@democratiCrayn 1 month ago

Market notes: Meta's AI hits travel stocks, Viking trial data, and high buyer income at KB Home

Market notes: Meta's AI hits travel stocks, Viking trial data, and high buyer income at KB Home
post thumbnail
avatar
@kewur 1 year ago

KB Home Dividend: Strong Earnings Growth, But Worrying Cashflow Payout

KB Home Dividend: Strong Earnings Growth, But Worrying Cashflow Payout

post thumbnail
avatar
@lestatdelion 3 years ago

Earnings Watch Updated

Earnings Watch Updated

This week's stock picks for MP_EarningsWatch: 

 Saratoga Investment Corp

Infosys Ltd

Taiwan Semiconductor Manufacturing

 KB Home

 United Health Group Inc

Powered by Froala Editor

No more topics to show